
ARR and NRR Commission Structures for SaaS Sales Teams
How to pay for new logos, renewals, and expansion separately.
Recurring revenue does not behave like a series of one-off sales, and commission plans built for one-off sales mispay for what SaaS businesses actually build. Each customer a company retains becomes the foundation on which next year's expansion and renewal get layered, so the compounding effect of retention, not the volume of bookings in a given quarter, is what boards and investors weigh when they judge ARR growth. A commission plan that ignores this compounding treats every dollar of bookings as identical, and that single assumption is where most SaaS comp plans go wrong before a single rate gets set.
SaaS revenue compounding and commission design
Consider what happens when a rep gets paid on a deal that churns after 90 days. The company has already written the commission check, and the recurring revenue that was supposed to justify that check has vanished, leaving a cost with no asset behind it. It is the predictable output of treating a churned renewal replacement, a freshly closed new logo, and an expansion upsell as economically equivalent events, when the underlying economics and the rep behaviors that produce them have almost nothing in common. A single-rate bookings structure cannot distinguish between a deal that compounds and a deal that evaporates, because it was never built to look past the moment of signature.
The distortion compounds further up the organization. A CRO or VP of Sales paid purely on net new ARR will, rationally and predictably, build an impressive pipeline sitting atop a customer base that leaks. The incentive to close is loud and immediate: it appears in the forecast within days. The incentive to qualify a deal for long-term fit is quiet and delayed, often invisible until a renewal cycle a year later exposes the mismatch. A commission structure that rewards only the loud signal will get more of the loud signal, and less of the quiet discipline that makes recurring revenue actually recur. Before any rate gets set, the plan has to decide which of these behaviors it is willing to pay for, because paying for all of them equally is the same as paying for none of them well.
How ARR and NRR measure different things
ARR measures the annualized value of subscription contracts in force at a given point in time. NRR measures something else entirely: what happened to that base of contracts over a period, combining expansion, contraction, and churn, and expressing the result as a percentage of the opening ARR. One is a snapshot of value currently on the books. The other is a trailing account of how well the business protected and grew that value once it already had it. They are two different outcomes, produced by different work, not two ways of describing the same outcome.
The two metrics pull commission design in opposite directions because they reward opposite behaviors. Maximizing new ARR rewards speed and volume in new-logo acquisition, the kind of behavior that is visible in a pipeline review within a week. Maximizing NRR rewards something slower: quality of customer fit at the point of sale, depth of onboarding, and the ongoing work of customer success that prevents contraction and drives expansion long after the initial contract is signed. These behaviors are not only different in kind, they are often controlled by different roles operating on entirely different timescales, an AE's quarter against a CSM's year. A flat rate applied uniformly to bookings rewards a fast close and a durable account the same way, because it was never designed to tell the two apart. The business needs both outcomes, so the compensation plan needs to pay for both outcomes separately rather than hoping one rate will produce both.
The three-rate architecture: what new-logo, renewal, and expansion commissions are each designed to do
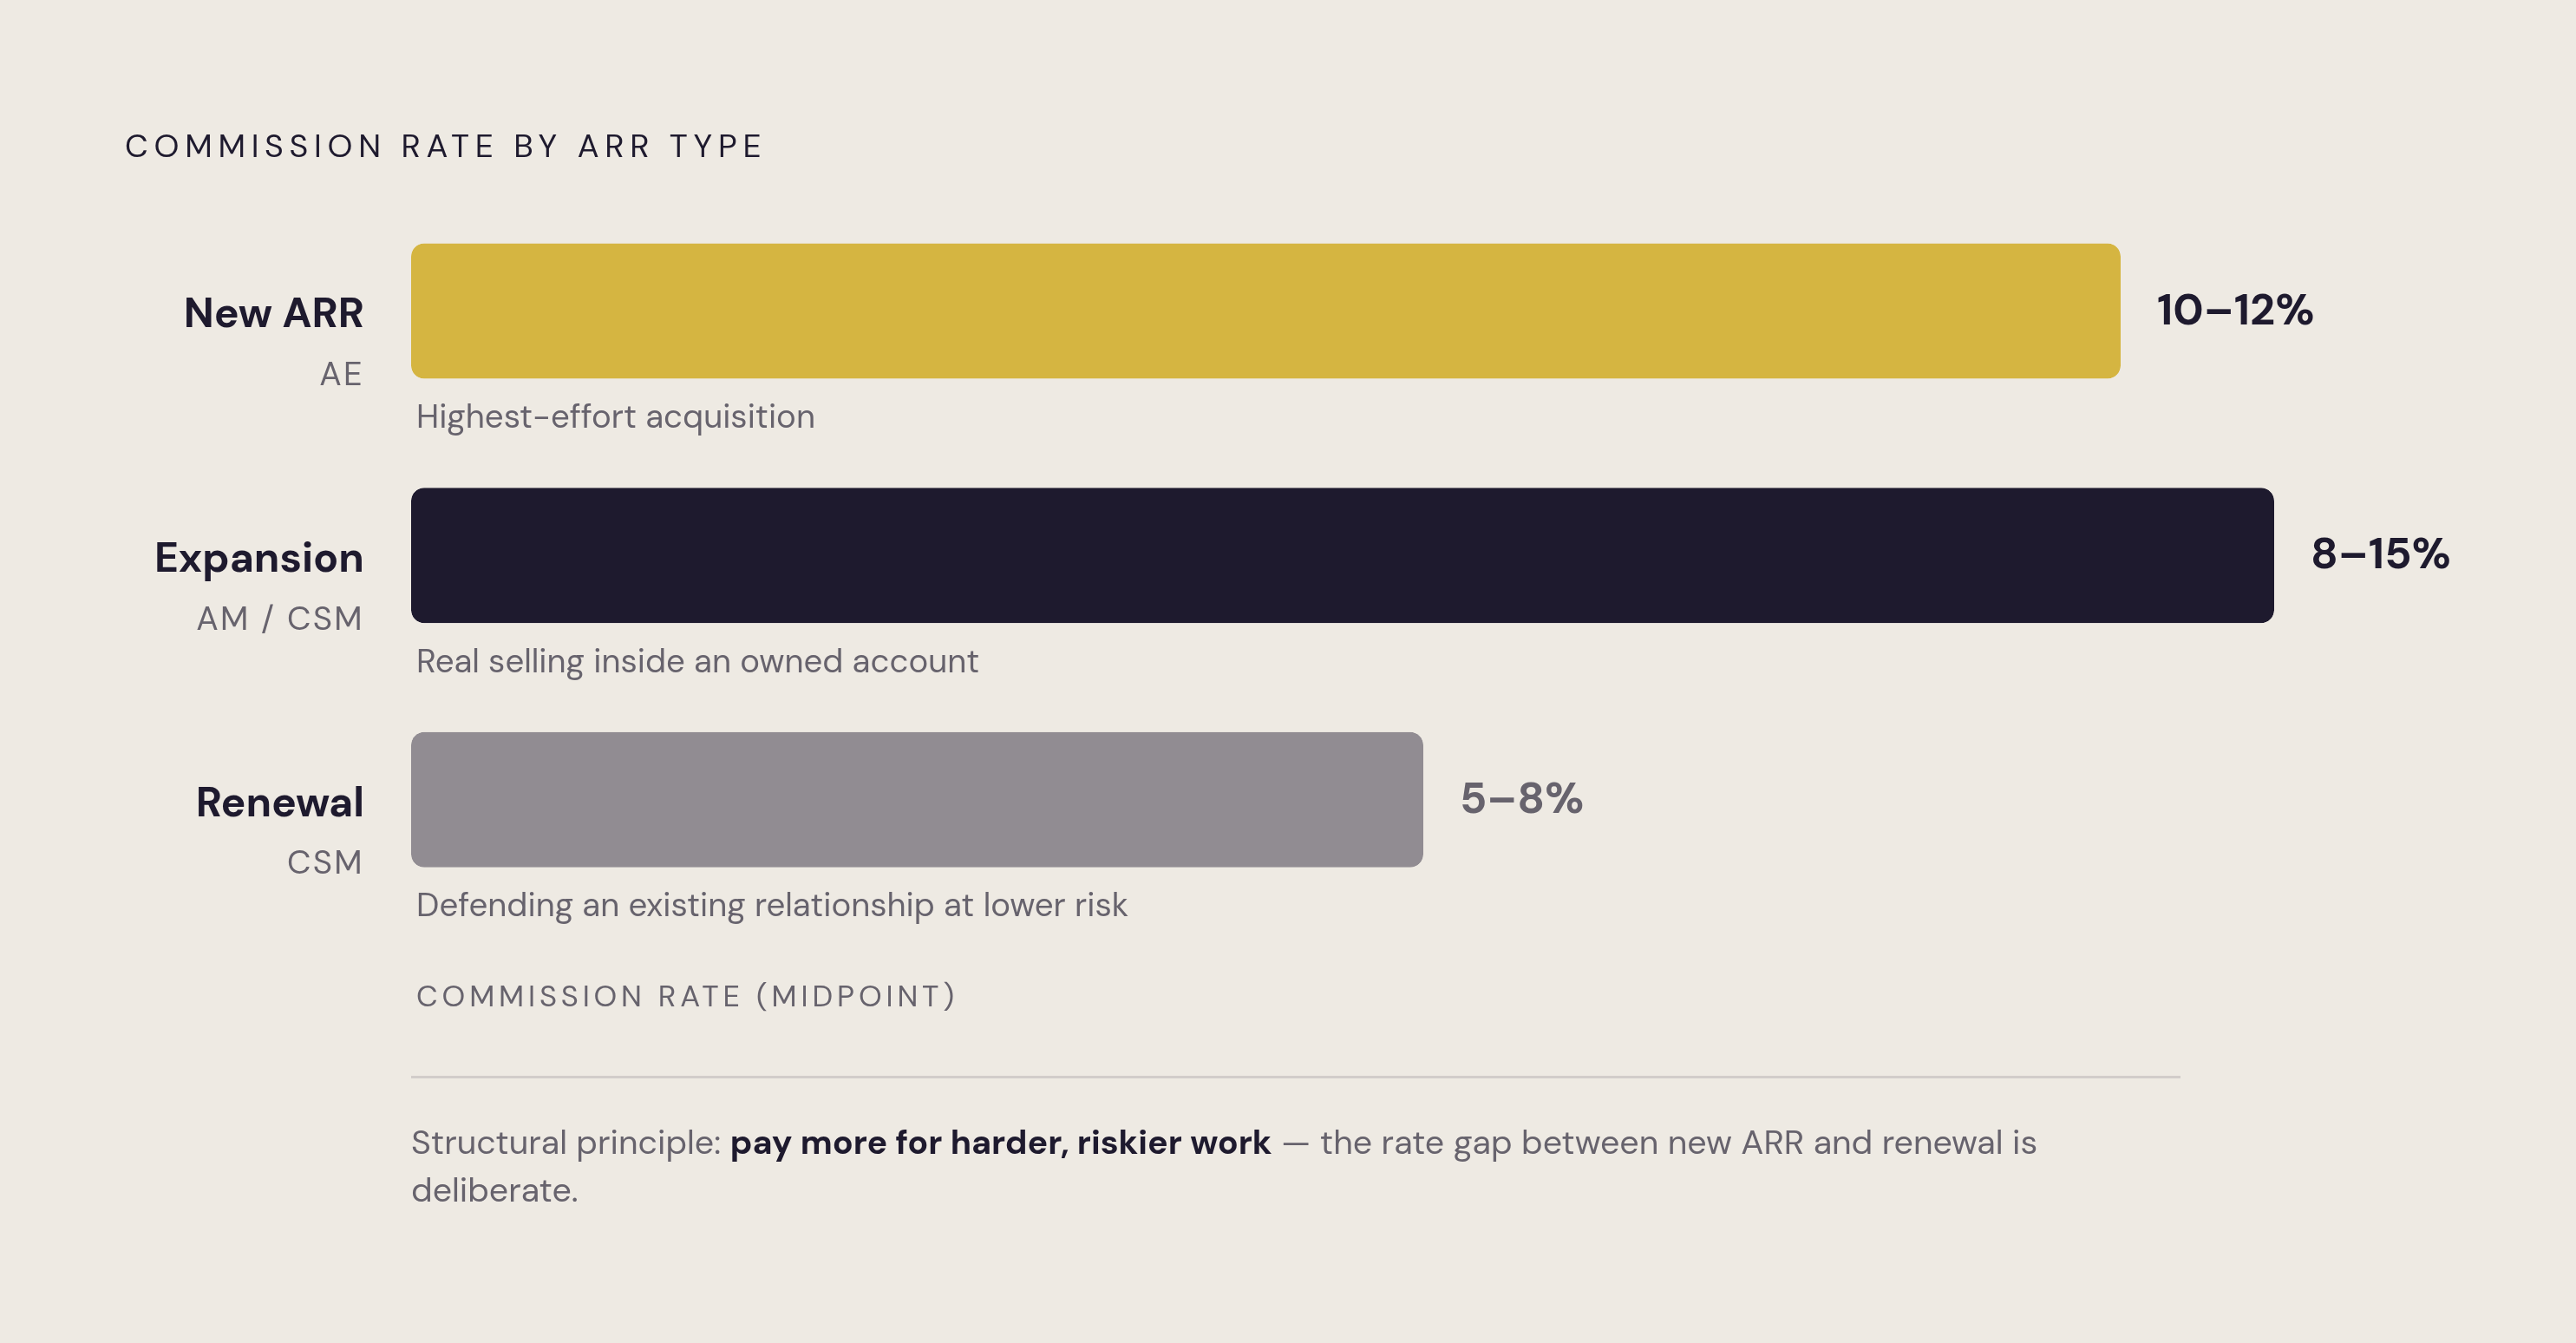
A well-designed SaaS commission plan resolves this by splitting into three separate levers, one for new ARR, one for renewals, and one for expansion, each paying a different rate because each is meant to reward a different behavior, from a different role, at a different point in the customer's life with the company. It is three distinct instruments pointed at three distinct problems, not three variations on the same payout.
New ARR commission, paid on new-logo acquisition, is the highest rate in the structure because acquiring a new customer from zero is the highest-effort, highest-risk activity in the entire go-to-market motion. Industry figures for 2026 put the average new-ARR commission rate for software and technology companies at 10% to 12% of annual contract value. Renewal commission is a noticeably lower rate, often in the 5% to 8% range, because the rep defending an existing relationship is working with far less risk and far less acquisition effort than the rep who built that relationship in the first place; paying a renewal at a new-logo rate inflates total comp cost without buying any additional behavior the business needs. Expansion commission, covering upsells and cross-sells into an existing account, tends to run higher than renewal, often 8% to 15%, reflecting that expansion requires real selling work even though it happens inside an account the company already owns.
They function as a framework, a starting architecture that gets constrained by the arithmetic of quota and OTE covered in the next section. What is fixed is the principle behind the split: a starting allocation of variable compensation weighted more toward net new ARR than toward net revenue retention, shifting that weighting toward retention as the company's ARR base grows, is a reasonable structural anchor for how much of a rep's total variable pay should be tied to each outcome. Early in a company's life, new-logo acquisition is existential, and the comp plan should say so. As the ARR base matures, the leverage in the business shifts toward protecting and expanding what already exists, and the comp plan should say that too. Customer success and account management roles carry a heavier share of the expansion incentive as that shift occurs, a discussion that deserves its own fuller treatment once the NRR targets themselves are on the table, but the core point holds even at this stage: the three rates are not static settings, they are a structure that moves as the business moves.
How the quota-to-OTE ratio locks the commission rate
None of the three rates above can be chosen freely once OTE and quota are set, because the commission rate is the output of a locked equation: OTE multiplied by the variable percentage, divided by quota, equals the commission rate. Set OTE and quota first, and the rate falls out of the math automatically. Borrowing the rate first from an industry benchmark or a blog post makes the plan quietly break somewhere else in the equation, usually in a quota that no longer matches what the business needs or an OTE that no longer matches the market for the role.
Work the equation with real numbers. The B2B SaaS median commission rate is 11.5% of annual contract value at full quota attainment, with quota typically set at four to six times OTE, the standard quota-to-OTE ratio across B2B SaaS. Divide the variable pay by the quota, and the commission rate that falls out is exactly 10%, sitting inside the standard 10% to 12% range for new ARR. It is what happens when OTE, quota, and pay mix are set deliberately and the rate is left to be the output rather than the input.
Pay mix itself follows a pattern by role that reflects how much control each role has over the final deal. An equal base-to-variable split is the 2026 standard for closing AEs across SMB and mid-market segments, because the AE has direct control over whether the deal closes. Enterprise roles shift slightly more toward base, reflecting longer sales cycles and more deal factors outside any one rep's control. SDRs weight heavily toward base because they control a meeting, not a closed deal, and a plan that over-indexes their pay on outcomes they cannot directly produce will mismeasure their contribution. Sales leaders lean toward base as well, because the systems they manage take entire quarters to move, and a highly variable plan tied to short-term results would reward the wrong timescale of work. In every case, the ratio of base to variable is set by how much control the role has over the outcome being paid for, and the commission rate is simply what is left once that control has been priced in.
Accelerator design, clawbacks, and the multi-year deal
Three mechanics inside the plan decide whether the rate structure built above actually changes rep behavior or just sits on paper: accelerator design, clawback policy, and the handling of multi-year deals. These are the places where SaaS commission plans most often get the incentive wrong, either by capping upside that should stay uncapped, by running clawback windows so wide they drive top performers to competitors, or by paying out multi-year total contract value at signing in a way that creates a real accounting liability.
Accelerators exist to reward overperformance, paying a higher rate once a rep clears 100% of quota. A strong majority of SaaS companies run accelerators, and fewer than 15% impose a commission cap, leaving top earners with uncapped upside. A cap on commission is the single mechanism most likely to push a top performer out the door, because the reps earning the largest checks are dramatically more cost-effective, per dollar of revenue produced, than median performers, and a cap on their pay tells them the company does not believe its own math. Where genuinely unusual deals create concern, such as a single enormous contract that would pay out an outsized check, a whale-deal review clause handles the exception without capping every rep's upside as a blanket policy.
Clawbacks address a narrower problem: deals that do not survive, whether through non-payment or immediate churn. Scalerr's research finds that roughly half of SaaS companies run clawbacks, typically on a short churn window, and that narrow implementation is the market norm rather than the exception. The discipline that makes clawbacks work is keeping the window short, applying it narrowly to cases of non-payment or near-immediate churn, and putting the terms in writing before the rep signs the offer. Reps price clawback risk into what they will accept from an employer, and the strongest candidates simply decline offers carrying broad, long-window clawback terms. There is a legitimate case against clawbacks altogether, made by the top performers who have the leverage to choose where they work: a rep who closes a good-faith deal that later churns for product or market reasons beyond their control should not have that commission reclaimed. Clawbacks should guard against gaming the system, not serve as a mechanism to reclaim pay from reps who did their job correctly and watched the market do something else.
Multi-year deals raise a separate problem entirely: how to reward a rep for selling contract length without creating a liability on the finance team's books. The practical structure pays the rep full commission rate on the first year's ACV at signing, not spread across the life of the contract, because a rep who closes a three-year deal should see that result in the next paycheck rather than in installments trickling out over three years. If the reward is spread as thin as the contract term, the incentive to sell length in the first place disappears. Years two and three then pay out at a reduced rate, and only when those years actually invoice, so the rep retains a reason to sell a longer contract while finance pays against cash that has actually arrived rather than revenue the company has not yet earned. For usage-based or consumption-based components, increasingly common in vertical SaaS products with embedded payments or fintech features built in, a hybrid structure works best: pay upfront at the committed amount, then true up the commission once actual consumption is known.
The growth-stage ARR range where the operational objection is valid
An ARR-split commission model requires clean ARR accounting and a system that can distinguish new, expansion, and renewal in real time, and many SaaS companies at an early ARR stage lack that data infrastructure, making a flat-rate ACV commission with manual NRR bonuses the pragmatic default rather than a failure of ambition.
The sales organization at this stage has outgrown improvisation but has not yet earned the budget for full commission infrastructure, and that mismatch is exactly where things break. A team small enough that a spreadsheet still feels manageable, paired with comp rules now complex enough that a spreadsheet's failure becomes expensive, is a genuinely difficult combination to manage well. The operational risk at this stage is rarely that the spreadsheet fails. It is that it fails silently, producing numbers that look plausible until an AE's own math stops matching Finance's math. Once that mismatch appears even once, AEs build their own shadow spreadsheets to double-check every commission payout before trusting it, and that habit, multiplied across a 20-person AE team each spending a few hours a month maintaining a shadow ledger, adds up to dozens of hours of selling time lost every month to reconciliation work that should never have been necessary. The last few days of the month tend to turn into a negotiation between Sales and Finance rather than a routine close.
Given that constraint, building a full three-rate, real-time-split ARR commission model is not the pragmatic move at this stage, and attempting it anyway is often what produces the shadow-accounting problem in the first place. A flat-rate commission on ACV, paired with a manual NRR bonus calculated periodically rather than split in real time, is the sound default for a company that has not yet built the data infrastructure the fuller model requires. It is the correct sequencing: architecture before automation, and automation before precision that the business cannot yet verify. The three-rate model remains the target worth building toward, but only once the ARR accounting can actually support the split it promises.
Sources
- A Complete Guide to Net Revenue Retention (NRR) in 2026
- Net Revenue Retention (NRR) Explained | SaaS Valuation Guide 2026 | FE International
- How Much to Compensate SaaS Sales Teams for New Sales, Renewals and Expansions | Tomasz Tunguz
- SaaS Sales Commission Rates: What's Standard in 2026? | Carvd
- SaaS Sales Team Structure by Stage: How to Build from $0 to $10M+ ARR - UltraTalent

